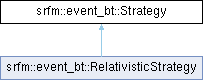
Abstract strategy interface. Subclass and override the virtual methods. More...
#include <event_backtester.hpp>
Public Member Functions | |
| virtual | ~Strategy ()=default |
| virtual void | on_start () |
| Called at the start of the simulation before any events are dispatched. | |
| virtual void | on_end () |
| Called at the end of the simulation after all events are processed. | |
| virtual std::optional< Order > | on_trade (const BacktestEvent &) |
| virtual std::optional< Order > | on_bar (const BacktestEvent &) |
Detailed Description
Abstract strategy interface. Subclass and override the virtual methods.
Definition at line 139 of file event_backtester.hpp.
Constructor & Destructor Documentation
◆ ~Strategy()
|
virtualdefault |
Member Function Documentation
◆ on_bar()
|
inlinevirtual |
Called for every Bar-type event.
- Returns
- An Order to execute, or std::nullopt for no action.
Reimplemented in srfm::event_bt::RelativisticStrategy.
Definition at line 159 of file event_backtester.hpp.
◆ on_end()
|
inlinevirtual |
Called at the end of the simulation after all events are processed.
Definition at line 147 of file event_backtester.hpp.
◆ on_start()
|
inlinevirtual |
Called at the start of the simulation before any events are dispatched.
Reimplemented in srfm::event_bt::RelativisticStrategy.
Definition at line 144 of file event_backtester.hpp.
◆ on_trade()
|
inlinevirtual |
Called for every Trade-type event.
- Returns
- An Order to execute, or std::nullopt for no action.
Reimplemented in srfm::event_bt::RelativisticStrategy.
Definition at line 152 of file event_backtester.hpp.
The documentation for this class was generated from the following file:
- include/srfm/event_backtester.hpp
